Buying a home here follows the same order every time. You find out what a lender will lend, you line up the cash, you learn the few Michigan rules that change the monthly payment, and then you look, offer, inspect, appraise, and close. Each step has its own paperwork and its own deadline, and most problems come from a step that got skipped or rushed.
This guide walks through all ten, with the real numbers. Where a figure depends on your loan or your house, it says so and tells you who gives you the exact one.
Getting pre-approved
Start with a lender, not with listings. A pre-approval is a lender reviewing your income, your savings, and your credit, then putting in writing how much they will lend and on which loan program. A pre-qualification is only an estimate built from what you told them. Sellers and their agents know the difference, and an offer without a real pre-approval behind it usually waits at the bottom of the pile.
What the letter actually means
The letter is a conditional yes. It says the lender has checked your file and will lend up to a stated amount, as long as the house appraises, the title is clear, final underwriting signs off, and nothing in your finances changes before closing. It is not a loan commitment, and it carries a date. Ask how long yours is good for and when it needs to be refreshed.
The number on the letter is the most you can borrow, not the amount you should spend. Budget from the monthly payment instead: principal and interest, property taxes, homeowners insurance, and mortgage insurance if your loan has it. Rates move, too. The 30-year fixed went from 6.66 percent at the end of August 2026 to 7.03 percent at the end of September (Freddie Mac weekly average), so a letter written before a jump like that may not cover the same price now. If yours is more than a few weeks old when you find the house, have it re-run before you write the offer.
Documents to gather
Lenders ask for the same things in almost every file, and having them ready is the easiest way to keep a closing on schedule:
- Pay stubs covering the last 30 days.
- W-2s for the last two years, and 1099s if you have them.
- Federal tax returns for the last two years, with every schedule. If you are self-employed, add your business returns and a year-to-date profit and loss statement.
- Bank statements for the last two months, every page, for every account you will use. Large deposits that are not paychecks will need a paper trail.
- Retirement and investment statements if those accounts are part of your savings.
- A photo ID, and if family is giving you money toward the purchase, a signed gift letter.
- Anything that explains a change, such as a divorce decree, a child support order, or a letter about a gap in employment.
Once you apply, the lender has three business days to send you a Loan Estimate, a standard form that shows the rate, the fees, and the cash you will need. Every lender uses the same form, so you can lay two or three side by side and compare them line by line. Fees differ between lenders more than people expect.
Credit basics
Lenders usually pull your report from all three credit bureaus and use the middle score. The score sets which programs you qualify for and what you pay: FHA allows 3.5 percent down with a score of 580 or higher, and on a conventional loan a higher score lowers both the rate and the cost of mortgage insurance.
Check your reports before a lender does, for free, at AnnualCreditReport.com, and dispute anything that is wrong early, because corrections take time. Pay every bill on time, keep credit card balances low compared with their limits, and leave old accounts open. Rate shopping does not hurt you much: scoring models count several mortgage inquiries in a short window as one.
Between pre-approval and closing, keep your finances still. Do not open new credit, finance a car or furniture, co-sign for anyone, move large sums between accounts without a record, or change jobs without telling your lender first. Any one of those can change the approval days before closing.
What you need in cash
The cash to buy a home comes in four parts: the down payment, the closing costs, the earnest money deposit (which is part of the first two, paid early), and whatever reserves your loan or your own comfort requires. Twenty percent down is one option, not the rule.
Down payment by loan type
| Loan | Minimum down | Who it fits | The extra cost to know |
|---|---|---|---|
| Conventional | From 3 percent | 3 percent is for qualifying first-time or income-eligible buyers; 5 percent is the usual minimum otherwise. | Private mortgage insurance below 20 percent down, which can come off as you build equity. |
| FHA | 3.5 percent | Buyers with a credit score of 580 or higher; smaller savings or a thinner credit history. | A mortgage insurance premium, paid up front and monthly. |
| VA | 0 percent | Eligible veterans, service members, and some surviving spouses. | No monthly mortgage insurance; a one-time funding fee, which some veterans are exempt from. |
| USDA | 0 percent | Homes in eligible rural areas, for households under the program's income limits. | A guarantee fee, paid up front and yearly. |
USDA matters more here than people think. Large parts of the countryside around West Michigan's cities are eligible, and buyers looking at a house on a few acres outside town are often surprised it qualifies. Eligibility is set by address and household income, so ask your lender to check the specific property.
| Down payment | On $300,000 | On $393,138 |
|---|---|---|
| 3 percent | $9,000 | $11,794 |
| 3.5 percent | $10,500 | $13,760 |
| 5 percent | $15,000 | $19,657 |
| 20 percent | $60,000 | $78,628 |
$393,138 is the average sale price across the 15 West Michigan counties Legacy covers in September 2026.
Closing costs
Closing costs run about 2 to 3 percent of the price, on top of the down payment. On a $300,000 home that is roughly $6,000 to $9,000. They fall into four groups: lender fees for making the loan, title work and title insurance, government recording fees, and prepaid items. The prepaids are your own money set aside for your own bills: interest to the end of the closing month, the first year of homeowners insurance, and a few months of property taxes and insurance placed in an escrow account. Michigan purchases also split the year's property taxes between buyer and seller by the closing date.
A seller can agree to pay part of your closing costs, called a seller concession, and each loan program caps how much. A lender credit in exchange for a slightly higher rate is another way to bring less cash. Both are worth asking about before you write the offer, not after.
Earnest money
Earnest money is a good-faith deposit made after your offer is accepted, usually about 1 to 2 percent of the price, so $3,000 to $6,000 on a $300,000 home. It is held in escrow by the listing brokerage or the title company and credited toward your down payment and closing costs at closing. It is not an extra cost. Chapter six covers when it is due and when it is at risk.
Reserves
Reserves are the savings left after closing. Some loans require them, counted in months of your full house payment, and your lender will tell you if yours does. Even when they are not required, plan for a cushion: the inspection and the appraisal are each usually a few hundred dollars paid before closing, and moving, utility deposits, and the first repair all arrive in the first month.
Michigan specifics
Three Michigan rules change what a house really costs: how property taxes reset after a sale, what to check on a rural well and septic system, and what the seller has to tell you in writing.
Property taxes uncap after a sale
Michigan taxes a home on its taxable value, not its price. Every home has a state equalized value, or SEV, which is about half of what the assessor thinks it would sell for. While one owner holds the home, its taxable value can only rise each year by the rate of inflation or 5 percent, whichever is lower, so after years of ownership the taxable value often sits well below the SEV.
When the home sells, that cap comes off. In the year after the sale, the taxable value resets to the SEV. The seller's tax bill is not your tax bill, and the difference can be large on a home that has had the same owner for a long time.
| An illustration | Seller now | You, the year after |
|---|---|---|
| Market value | $300,000 | $300,000 |
| SEV (about half) | $150,000 | $150,000 |
| Taxable value | $95,000 | $150,000 |
| Tax at 40 mills | $3,800 | $6,000 |
A mill is $1 of tax per $1,000 of taxable value. Rates are set locally and vary by city, township, and school district, so look up the actual millage for the address.
Ask for the SEV and the millage on any home you are serious about, and budget from the uncapped number, not from what the seller pays now.
The homestead exemption
If the home will be your primary residence, file a Principal Residence Exemption affidavit, often called the homestead exemption, with the city or township assessor. It exempts your home from up to 18 mills of local school operating tax, every year you own and live in it. It is not automatic. File it by June 1 to have it on that year's summer and winter bills, or by November 1 to have it on that year's winter bill. Title companies often hand you the form at closing, and signing it there is the easiest way to not miss it.
The July and December bills
Michigan homes get two property tax bills a year: the summer bill, issued in July, and the winter bill, issued in December. Due dates are set by each city or township. If your loan has an escrow account, your lender collects part of the tax with each monthly payment and pays both bills for you.
Well and septic in rural areas
Outside city water and sewer, the house has its own well and its own septic system, and both deserve their own inspections, separate from the general home inspection. For the well, that means a water test for bacteria and nitrates, plus a check of the pump and how much water it delivers. For the septic system, that means having the tank pumped and the tank and drain field looked at by a septic company. A failed drain field is one of the most expensive surprises a rural house can hold.
Some Michigan counties and townships require a well and septic evaluation whenever a home changes hands, and others do not, so ask what applies to the parcel. Many lenders, especially on FHA, VA, and USDA loans, also require a water test before closing.
The seller's disclosure
Michigan's Seller Disclosure Act requires the seller of most homes with one to four units to give you a written Seller's Disclosure Statement. It covers what the seller knows about the roof, the basement, water and sewer, the mechanical systems, past repairs, and other conditions. It reports what the seller knows; it is not a warranty and not a substitute for an inspection. Read it before you write your offer, and ask about anything marked unknown.
If the disclosure reaches you after you have signed an offer, you can end the deal by written notice within 72 hours if it was handed to you, or 120 hours if it was mailed. For a home built before 1978, the seller also has to give you a federal lead-based paint disclosure, and you have the chance to arrange a lead inspection, usually within 10 days, unless you choose to waive it.
Choosing where to live
West Michigan is not one market. Lakeshore towns, the Grand Rapids and Kalamazoo areas, and the inland and northern counties each have their own prices and their own pace. Here is how the 15 counties looked in September 2026.
| County | Sold | Avg price | Days |
|---|---|---|---|
| Kent | 610 | $442,795 | 24.6 |
| Ottawa | 299 | $484,533 | 31.7 |
| Kalamazoo | 262 | $344,008 | 25.8 |
| Muskegon | 200 | $306,439 | 32.9 |
| Allegan | 122 | $440,360 | 29.4 |
| Barry | 64 | $375,623 | 25.3 |
| Montcalm | 59 | $315,846 | 19.8 |
| Newaygo | 52 | $290,625 | 36.3 |
| Mason | 47 | $333,278 | 40.5 |
| Oceana | 42 | $382,643 | 67.0 |
| Ionia | 42 | $266,744 | 37.6 |
| Mecosta | 36 | $305,698 | 46.6 |
| Manistee | 30 | $311,912 | 42.0 |
| Lake | 26 | $205,331 | 37.8 |
| Osceola | 19 | $228,692 | 75.7 |
| All 15 | 1,910 | $393,138 | 30.2 |
Residential closings in September 2026, counted October 6, 2026, from the brokerage's monthly market data. Days are average days on market. This month's numbers are on the Insights page.
A few things in that table are worth reading closely. Kent County had nearly a third of all the sales, and homes there sold in under 25 days on average. Ottawa had the highest average price. The northern and inland counties had the lowest prices and, in places like Oceana and Osceola, the longest wait for a seller, which can mean more room to negotiate for a buyer.
How to narrow it down
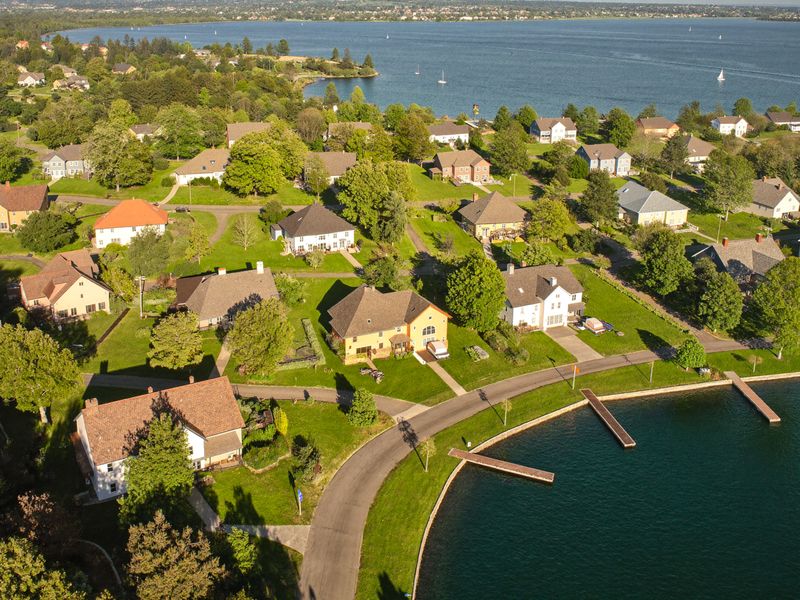
Start with what your days actually run on. Drive the commute at the hour you would really make it, in both directions. Look up the school district by the exact address, because district lines in Michigan do not follow city lines, and two houses on the same road can be in different districts. Check whether a house is on city water and sewer or a private well and septic system, since that changes both the inspection and the upkeep.
Then look at the costs that change by location. Millage rates differ from one township to the next, so two similar homes a few miles apart can carry very different tax bills. Homes near Lake Michigan, inland lakes, and rivers may sit in a flood zone that requires flood insurance, which your lender will check. If you are thinking about renting the place out part of the year, read the city or township's short-term rental rules before you buy. And winter is real: lake-effect snow falls heavier in some areas than others, which matters for a long driveway or a daily drive.
Touring and comparing homes
Before the first showing, split your list in two: what you need and what you would like. Needs are bedrooms, the commute, the school district, the budget, and anything your daily life depends on. Wants are everything else. The split keeps you from falling for a house that misses a need, and it makes the search faster.
New listings that fit your search can reach you the day they hit the market. The first days of a listing are when it gets the most attention from other buyers too, so plan to see the right ones quickly.
What to look at in a house
Photos show finishes. A showing is the time to look at the things that cost real money. Note the age of the roof, the furnace, the air conditioner, and the water heater. Look at the windows, the foundation walls, and the basement for water stains, a musty smell, or fresh paint in odd places. Check which way the ground slopes around the house and where the downspouts drain. Open the electrical panel door and look at the outlets near water. None of this replaces an inspection, but it tells you which houses are worth one.
Comparing two or three homes
When you are down to a few, compare them on the real monthly cost, not the list price. Put each one through the same numbers:
- The payment at the price you would offer, from your lender.
- The taxes after the sale, from the SEV and the local millage, not from the seller's bill.
- Insurance, quoted for that address, plus flood insurance if the home is in a flood zone.
- Utilities and upkeep: the heating type, the age of the big systems, and a well and septic system if there is one.
- Association dues and rules for a condo or a neighborhood with an association.
See your top choice a second time, at a different time of day. Note how long it has been on the market and whether the price has changed. A home that has sat for weeks or had a price cut is telling you something about how much room there is to negotiate.
Writing the offer
The offer is a purchase agreement, and once the seller accepts it in writing it is a binding contract. Price is the loudest part, but the seller reads the whole thing, and the terms decide what you are protected from.
Price
Your price comes from what similar homes nearby sold for in the last 90 days, adjusted for size, condition, and updates, with an eye on how long this one has been for sale. A home that just listed and has several showings booked is a different negotiation from one that has sat for two months.
Terms
Besides the price, the agreement spells out your loan type and how much you are putting down, the earnest money, the closing date, when you get possession, any seller concession toward your closing costs, what stays with the house, and how long the seller has to answer. A clean offer with strong financing and a sensible timeline can beat a higher one that looks uncertain.
Contingencies
Contingencies are the conditions that let you leave the deal and keep your earnest money. The common ones are the inspection contingency, which gives you a set number of days to inspect and respond; the financing contingency, which protects you if the loan falls through; the appraisal contingency, which protects you if the home appraises below the price; and, if you need to sell first, a contingency on the sale of your current home. Each one has a deadline in the agreement. Waiving one makes an offer stronger and takes away a protection, so know exactly what you are giving up.
The earnest money timeline
The amount goes in the offer. The purchase agreement sets when it is due, usually within a few days of acceptance, and who holds it, usually the listing brokerage or the title company. From there it sits in escrow until closing, where it is credited to you.
If the deal ends inside a contingency, for a failed inspection, a loan denial, or a low appraisal, and you give notice within its deadline, the purchase agreement normally returns the deposit to you. If you walk away outside those protections, it can go to the seller. If the two sides disagree, the escrow holder usually waits for both to sign a release, so the deadlines in your agreement are the ones to put on your calendar.
| When | What happens |
|---|---|
| Day 0 | The seller accepts in writing. Your contract dates start. |
| A few days in | Earnest money is due, by the date in the agreement. You apply for the loan formally if you have not already. |
| The first week or two | Inspections, and your response to them, inside the inspection window. |
| Weeks two to four | The appraisal and underwriting. The title company runs the title search. |
| Three business days before closing | Your Closing Disclosure arrives, with the final loan terms and cash to close. |
| Day 30 to 60 | Final walkthrough and closing. |
A typical financed purchase. Your purchase agreement sets the actual dates.
Inspection and repairs
The inspection is yours. You choose the inspector, you pay for it, and you decide what matters in the report. Go to it if you can. An hour of walking the house with the inspector teaches you more than the report does, and you learn where the shutoffs are.
What to ask for
A general home inspection covers the structure, the roof, the plumbing, the electrical system, heating and cooling, and the visible condition of the rest. A few tests are worth adding. Radon is a gas you cannot see or smell, it is common in Michigan homes, and the only way to know the level is to test; the federal action level is 4 picocuries per liter. A camera look at the sewer line is worth it on an older house or one with big trees in the yard. A rural home needs the well and septic inspections from chapter three.
How repairs get negotiated
Every report has a long list. Sort it. Safety problems, water getting in, and systems at the end of their life are worth asking about. Cosmetic items, small fixes, and things you saw at the showing are not. A focused request gets taken seriously; a request for everything invites a no.
There are four ways the seller can answer: make the repairs before closing, give you a credit at closing, lower the price, or decline. If repairs are made, ask for receipts and check them at the final walkthrough. A credit is often simpler, but lenders limit how much credit you can receive, so confirm the amount works with your loan. If you cannot reach an agreement, the inspection contingency lets you walk away with your earnest money, as long as you give notice within its deadline.
Some loans add their own list. FHA, VA, and USDA appraisals can call for certain safety or condition repairs before the loan will close, whatever you and the seller agreed.
The appraisal
When you finance a home, the lender orders an appraisal to confirm the house is worth what you are paying. A licensed appraiser looks at the home and compares it with recent sales of similar homes nearby. The lender then lends on the lower of the contract price or the appraised value.
If it comes in low
A low appraisal does not end the deal by itself. It means the loan gets smaller, and the difference has to come from somewhere. Here is how the math works:
| 5 percent down | Appraises at price | Appraises low |
|---|---|---|
| Contract price | $300,000 | $300,000 |
| Appraised value | $300,000 | $285,000 |
| Largest loan (95 percent) | $285,000 | $270,750 |
| Cash for the down payment | $15,000 | $29,250 |
From there you have four paths. First, read the report: check the square footage, the updates, and the comparable sales, and if the appraiser missed something or used poor comparisons, the lender can submit a request for reconsideration with better recent sales. Second, renegotiate: the seller lowers the price, you bring more cash, or you split the gap. Third, if your agreement has an appraisal contingency and you give notice inside its deadline, you can leave with your earnest money. Fourth, your loan officer can tell you whether a different loan program or down payment changes the picture. Which path is right depends on your cash and on how much other interest the seller has.
Walkthrough and closing day
Three business days before closing, your lender sends the Closing Disclosure: the final rate, the final fees, and the exact cash you need to bring. Compare it with your Loan Estimate and ask about anything that changed. The title company's settlement statement, which lists every credit and charge for both sides, often comes later, sometimes the day before closing. That is normal. Have it checked line by line against the Closing Disclosure and the purchase agreement as soon as it arrives.
The final walkthrough
Usually within a day or so of closing, you walk the house one last time. You are checking that agreed repairs were made (bring the receipts), that the appliances and fixtures in the agreement are still there, that nothing new is damaged, and that the heat, water, lights, and appliances all work. If something is wrong, it gets resolved before you sign, not after.
What you sign
At the closing table, the title company walks you through each document. You sign the Closing Disclosure; the promissory note, which is your promise to repay the loan; the mortgage, which pledges the home as security for that loan; the settlement statement; and a set of affidavits and loan forms. Many title companies also have you sign the homestead exemption affidavit and the Property Transfer Affidavit, which has to reach the assessor within 45 days of the sale. The seller signs the deed. Bring a government photo ID and your funds in the form the title company tells you, usually a wire or a cashier's check.
When you get the keys
Possession is set in the purchase agreement. Usually it transfers at closing, once the loan has funded and the documents are signed, and you leave with the keys that day. If the seller needs a few days after closing to move out, that is written into the agreement ahead of time, usually with a daily charge and money held back at closing until they are out. The title company records the deed with the county register of deeds, and the house is yours.
After you move in
Two things in the first year cost real money if they slip: the homestead exemption filing and the first tax bills.
The homestead exemption deadline
If you did not sign the Principal Residence Exemption affidavit at closing, file it with your city or township assessor right away. Filed by June 1, it applies to that year's summer and winter bills. Filed by November 1, it applies to that year's winter bill. Close in August and file in September, and you have it on the December bill; wait until December, and that year's winter bill goes out without it. Keep a copy, and check your next tax bill to make sure the exemption is on it.
When the first tax bill arrives
Michigan tax bills go out in July and December, so your first one is whichever comes next after closing. The taxes for the part of the year before closing were already split with the seller on the settlement statement. If you have an escrow account, confirm the bill goes to your lender or forward it, and make sure the lender pays it.
The uncapped taxable value shows up the year after the sale. Late in the winter, the assessor mails a notice of assessment with the new taxable value, and the bills that follow it reflect your purchase. If you think the assessment is too high, the local Board of Review hears appeals in March, and the deadlines are firm.
Expect your escrow account to catch up, too. Escrow is usually set at closing from the seller's lower tax bill. When the lender reviews the account after the higher bills arrive, the monthly payment can go up to cover the difference. Knowing that ahead of time turns a surprise into a line in the budget.
Everything else in the first month
Keep your closing papers together in one place. Change the locks or rekey them. Find the water shutoff, the electrical panel, and the furnace filter size. Keep receipts for improvements you make to the home, and ask a CPA how they count when you eventually sell.